PACE Assessment on a Davie, FL Home: Buyer and Seller Guide
What is a PACE assessment, and how does it affect buying or selling a home in Davie?
A PACE assessment is a non ad valorem lien recorded against a Davie, Florida home to finance energy, solar, or hurricane hardening upgrades, and you repay it on your annual property tax bill. Under Florida Statute 163.08 it carries a lien equal in priority to county taxes. If your buyer uses an FHA, VA, Fannie Mae, or Freddie Mac loan, the balance usually has to be paid off at closing, and a seller has to disclose it in writing before the contract is signed.
I have watched a clean Davie deal stall three days before closing because nobody flagged a solar balance sitting on the seller’s tax bill. The buyer had an FHA loan, the lender would not fund over a first position PACE lien, and suddenly a five figure payoff had to come out of the seller’s proceeds. Here is what I tell every Davie buyer and seller so that surprise never lands on you.
How a PACE assessment ends up on a Davie home
PACE stands for Property Assessed Clean Energy. It is a financing program that lets a homeowner pay for certain upgrades over time through a special assessment on the property tax bill instead of a bank loan. Davie participates through the Broward County PACE program, and the Florida PACE Funding Agency is one of the providers operating in the county.
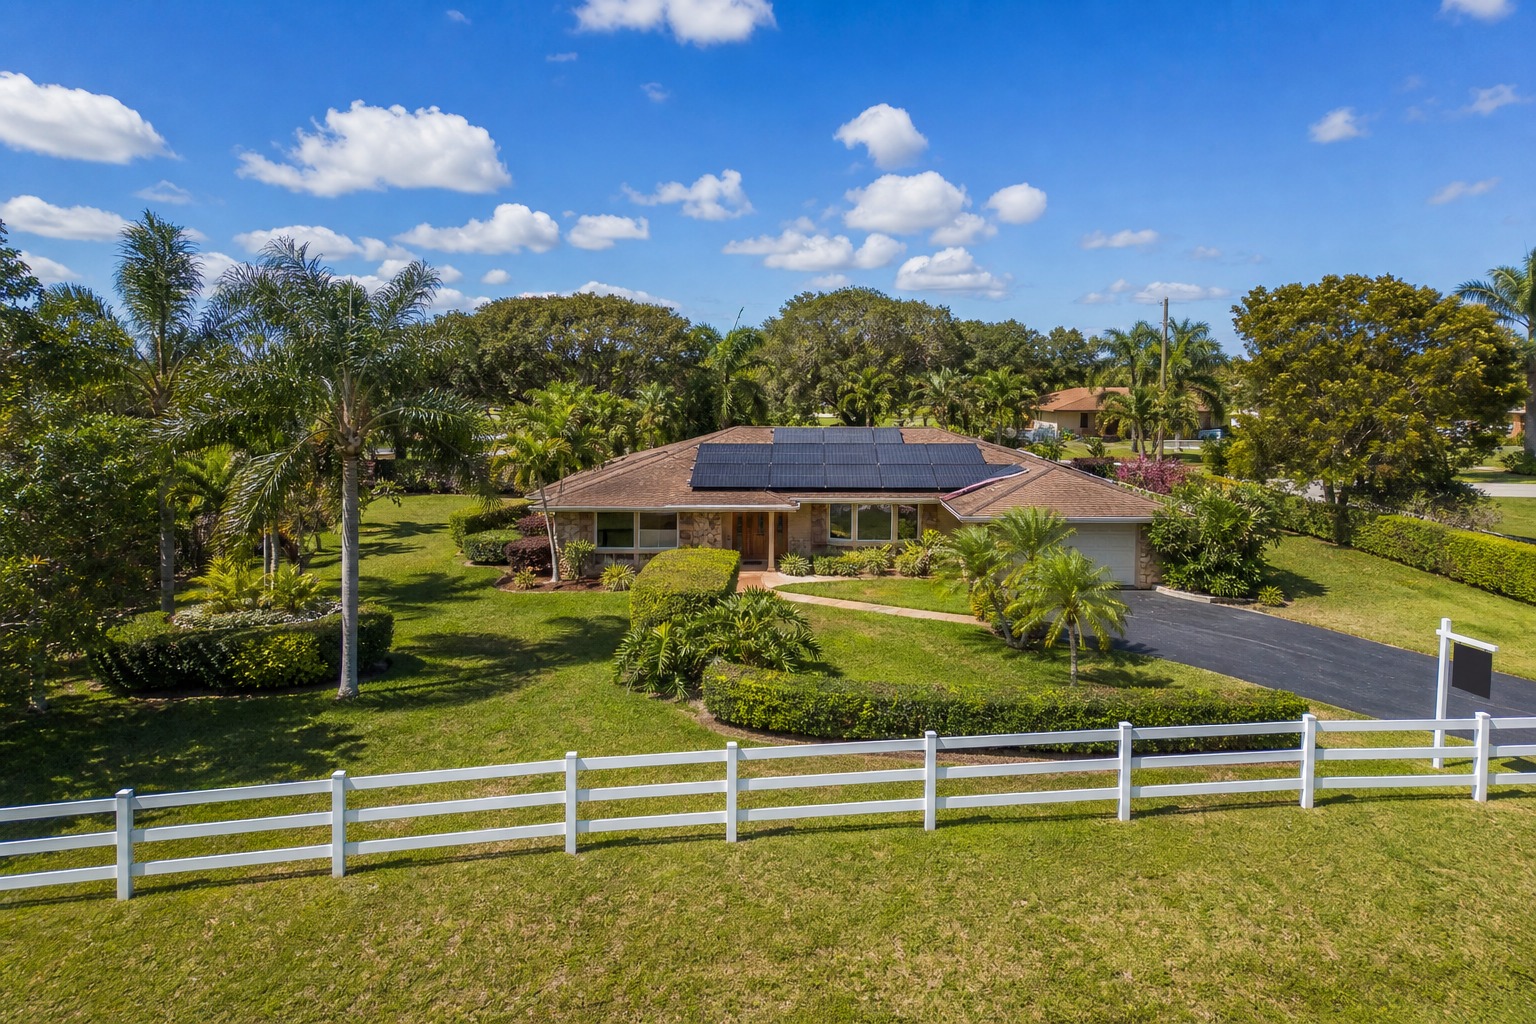
Under Florida Statute 163.08, PACE money can pay for three kinds of work: energy efficiency upgrades, renewable energy like solar, and wind resistance work such as a new roof, impact windows, storm shutters, and reinforced roof to wall connections. That last category is why PACE shows up so often on Davie homes. Owners use it to harden against hurricanes, sometimes as an alternative to the My Safe Florida Home grant, and solar buyers use it to finance panels, which is the same lien issue I cover in the guide on solar panels when buying or selling a Davie home.
The repayment is a non ad valorem assessment. That means it sits on your tax bill as a separate line item, apart from the ad valorem taxes based on your home’s value. You can see how those line items break down at the Broward County Property Appraiser, and it works alongside everything else in your Davie property tax bill. The key point is that the lien attaches to the property, not to the person, and it holds a priority equal to county taxes from the day it is recorded.
Selling a Davie home that has a PACE assessment
If you are selling, the first rule is disclosure. Florida Statute 163.08 requires you to give the buyer written notice before the purchase contract is signed that the property carries a PACE assessment. This is not optional, and it belongs with the rest of your Florida seller disclosure requirements.
The harder issue is financing. Federal housing agencies treat a first position PACE lien as a problem. The Federal Housing Finance Agency has stated that Fannie Mae and Freddie Mac should neither purchase nor refinance mortgages with a PACE loan attached, and FHA and VA take the same position. In plain terms, most buyers who need a conventional, FHA, or VA loan cannot close on your home until the PACE balance is paid off.
Here is what that means for your net proceeds. If your buyer is financing, plan for the payoff to come out of your side at closing, the same way a mortgage payoff does. Build it into your closing cost math early so it does not shrink your walkaway number at the last minute. A cash buyer can sometimes agree to take the assessment over, since the statute lets it stay with the property, but that is a negotiation, not a default. Do not assume it transfers.
One more detail worth knowing. The statute caps total PACE assessments at 20 percent of the home’s just value unless your mortgage holder consents, per Florida Statute 163.08. That cap tells you the balance is usually payable from equity in a normal Davie sale, where the current single family median is $893,000 (single-family median, trailing 178 days ending Sep 30, 2026, based on 196 listings, per BeachesMLS).
Buying a Davie home with a PACE assessment
If you are the buyer, a PACE assessment is not automatically a reason to walk. It is a reason to slow down and read the numbers. Ask three questions early. What is the current payoff balance? How many years remain on the assessment? And does your loan program allow it to stay in place?
If you are paying cash or using a loan that permits it, you may choose to keep the assessment and inherit the annual payment on the tax bill. If you are using an FHA, VA, or conventional loan, expect your lender to require the seller to clear it before closing. Either way, you want the balance and the annual amount in writing before your inspection period ends, because this is a due diligence item, not a closing day surprise. This is the same reason I push every buyer to know who pays for what at a Davie closing before they get to the table.
A quick note on rates. The interest rate on a PACE assessment is often higher than a traditional home equity loan or a cash out refinance, so paying it off is frequently the better long term move even when a program would let you assume it. Confirm the current rate, remaining term, and exact payoff with the PACE provider and verify the tax bill line items with the Broward County Property Appraiser before you decide.
How to check for and clear a PACE lien before you close in Davie
1. Pull the property tax bill and look for a non ad valorem assessment line labeled PACE, clean energy, or a provider name. Verify it at the county appraiser record.
2. Ask the seller in writing for the PACE provider, the current payoff balance, and the remaining term. The seller must disclose the assessment under Florida Statute 163.08.
3. Confirm with your lender whether your loan program allows the assessment to remain or requires payoff at closing.
4. If payoff is required, have the title company request a written payoff statement from the provider and build it into the closing figures.
5. Decide, with your agent, whether to negotiate the payoff into the seller’s costs or adjust your offer terms accordingly.
Every Davie situation is a little different, and the right move depends on your loan, the balance, and your timeline. This is exactly the kind of question I walk my clients through before we write or accept an offer.
Frequently Asked Questions
Does a PACE assessment transfer to the new owner when a Davie home sells?
The statute allows the assessment to stay with the property because the lien attaches to the home, not the owner. In practice, most buyers use FHA, VA, or conventional financing, and those lenders require the balance paid off at closing. Assuming it is possible mainly with a cash buyer who agrees to it.
Can I get an FHA or VA loan on a Davie home with a PACE lien?
Generally not while the PACE lien sits in first position. The Federal Housing Finance Agency has said Fannie Mae and Freddie Mac should not buy or refinance loans with PACE attached, and FHA and VA follow the same rule. The assessment usually has to be cleared before the loan can close.
Where does the PACE payment show up on my Davie tax bill?
It appears as a non ad valorem assessment, a separate line from the ad valorem taxes based on your home’s value. You can review the breakdown at the Broward County Property Appraiser record for your parcel.
What does PACE pay for on Davie homes?
Under Florida Statute 163.08, PACE funds energy efficiency upgrades, solar and other renewable energy systems, and wind resistance work like a new roof, impact windows, and storm shutters. Hurricane hardening is a common use across Davie, including acreage neighborhoods like Long Lake Ranches (33330).
Do I have to tell a buyer my Davie home has a PACE assessment?
Yes. Florida Statute 163.08 requires a written disclosure to the buyer before the purchase contract is signed. It belongs with your standard Florida seller disclosures, and hiding it can unravel the deal later.
Talk to a Davie Real Estate Expert
A PACE assessment is workable on both sides of a Davie deal, but only if you catch it early and run the numbers before you sign. If you are buying or selling a single family home in Davie and want to know exactly how a lien like this changes your bottom line, schedule a strategy call and we will walk through it together.
Anthony Spitaleri
Broker Associate, REALTOR® | Coldwell Banker Realty
Creator of Living in Davie, Florida
Davie, Florida | Serving Davie, Weston and surrounding Broward markets
954-235-5783
Florida License BK3281907
@livingindavieflorida
Written by Anthony Spitaleri, Broker Associate, REALTOR® with Coldwell Banker Realty and a Davie native. More about Anthony